I’ve lost count of how many founders I’ve watched bleed cash because they confused a payment gateway with a merchant account. They treat them like interchangeable software features. Big mistake. Huge. If you’re running an online store or a brick-and-mortar shop, misunderstanding this financial plumbing means you’re likely paying triple what you should in processing fees, or worse, facing sudden account freezes with zero warning.
Let’s clear the air. No corporate fluff. No overly sanitized definitions written by a PR team that has never processed a single refund. Here’s the ugly truth about how your money moves from a customer’s pocket into your bank account.
- • The Anatomy of a Transaction: Gateway vs. Bank
- • Aggregated Accounts Vs. Dedicated Accounts: Where the Rubber Meets the Road
- • The Financial Reality: Fees, Rates, and Markup
- • Security and Compliance: Don't Skip the Fine Print
- ↳ Do I need both a payment gateway and a merchant account?
- ↳ Why did my payment processor suddenly freeze my account?
- ↳ When should I transition from an aggregated account to a dedicated merchant account?
- ↳ Are payment gateways responsible for chargebacks?
Key Takeaways & Quick Overview
AI Verified
- ✔I’ve lost count of how many founders i’ve watched bleed cash because they confused a payment gateway with a merchant account.
- ✔They treat them like interchangeable software features.
- ✔If you’re running an online store or a brick-and-mortar shop, misunderstanding this financial plumbing means you’re likely paying triple what you should in processing fees, or worse, facing sudden account freezes with zero warning.
- ✔No overly sanitized definitions written by a pr team that has never processed a single refund.
The Anatomy of a Transaction: Gateway vs. Bank
To understand the difference, you first need to look at what happens the exact millisecond a customer clicks “Buy Now.” It feels instant. It isn’t.
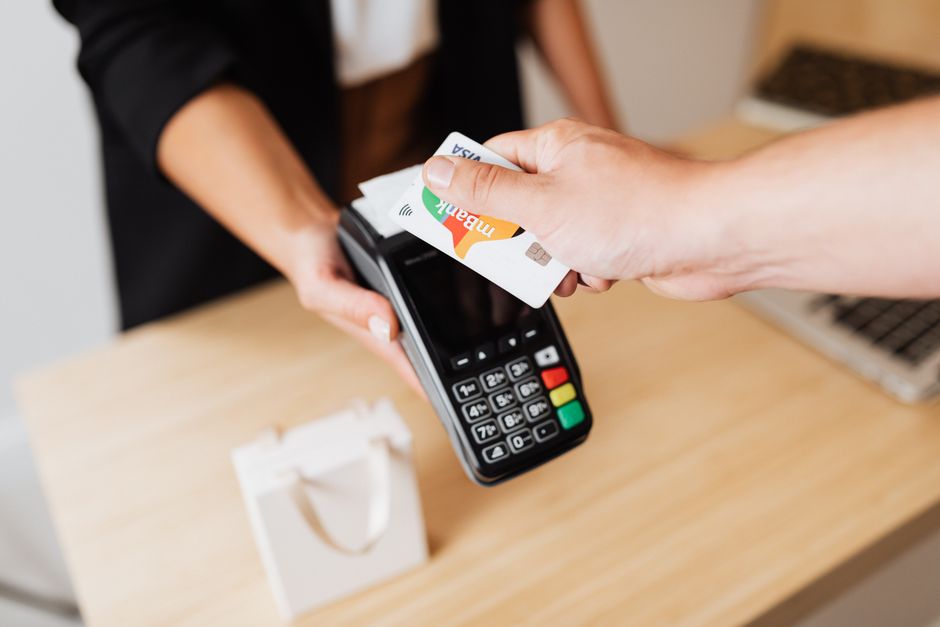
A payment gateway is the bouncer and the digital cashier. It lives on your website, sitting right there at the checkout page. Its sole job is to capture the customer’s credit card data, encrypt it so hackers can’t touch it, and safely pass it along down the line. It doesn’t hold your money. It doesn’t have a vault. It’s purely the secure messenger.
A merchant account, on the other hand, is your actual financial home. It’s a specialized bank account designed specifically to hold funds authorized from credit and debit card transactions before they finally settle into your primary business checking account. Without a merchant account, you have nowhere for the money to sit safely while the clearinghouses do their background checks.
Think of it this way:
- The Payment Gateway: The digital checkout lane and security guard.
- The Merchant Account: The secure holding tank where your revenue rests before hitting your bank.
Clear? Good. Because the confusion usually starts when third-party processors bundle both together.
Aggregated Accounts Vs. Dedicated Accounts: Where the Rubber Meets the Road
When you sign up for a popular, out-of-the-box setup like Stripe, Square, or PayPal, you are typically getting an aggregated merchant account (sometimes called an aggregated service provider). They lump you in with thousands of other businesses under *their* master merchant account.
Is it fast to set up? Absolutely. I’ve built entire checkout flows in under ten minutes using aggregated accounts. But convenience always comes with a hidden tax.
Because you share an account with the masses, you are exposed to their risk. If a rogue seller running dropshipping scams operates on the same aggregator platform, the payment networks might crack down globally. That means your legitimate business could wake up to a sudden account freeze or rolling reserve. Trust me on this—having $40,000 locked up for 180 days “for review” will completely paralyze your cash flow.
On the flip side, a dedicated merchant account is yours and yours alone. You get a unique Merchant Identification Number (MID). Underwriters look at *your* specific business model, *your* risk profile, and *your* volume. It takes longer to apply. You’ll need to submit profit and loss statements, personal guarantees, and past processing history. But once you’re approved? You get lower interchange-plus pricing rates, dedicated customer support, and true financial stability.
The Financial Reality: Fees, Rates, and Markup
Let’s talk numbers. Because if you aren’t watching your effective rate, you are slowly bleeding profit margins.
Aggregators love flat-rate pricing (e.g., 2.9% + $0.30 per transaction). It’s predictable. It’s easy to calculate. But if your average ticket size is high, or your volume scales past $10,000 a month, flat-rate pricing is a massive financial leak. According to data from the Federal Reserve payments study, digital transaction volumes continue to shatter records year over year, meaning even a fraction of a percent in processing waste scales into thousands of dollars lost.
With a traditional merchant account paired with a gateway, you usually deal with interchange-plus pricing. You pay the exact wholesale rate charged by Visa or Mastercard (the interchange fee), plus a tiny, transparent markup percentage paid to your processor.
Let’s break down the math:
- Flat Rate: You pay 2.9% on a $500 transaction ($14.50).
- Interchange-Plus: The base card rate might be 1.8%, plus your processor’s 0.2% markup (Total 2.0% = $10.00).
On a single transaction, saving four bucks doesn’t sound life-changing. But multiply that across five thousand transactions a month? That’s thousands of dollars staying in your operating account instead of lining a tech giant’s pockets.
Security and Compliance: Don’t Skip the Fine Print
You cannot talk about payment infrastructure without addressing security. Handling cardholder data is a legal minefield. Both gateways and merchant accounts have to adhere to strict PCI Security Standards Council regulations, but their roles in compliance differ vastly.
A good payment gateway ensures that raw credit card numbers never actually touch your web server. They use tokenization. When a customer enters their card, the gateway swaps it out for a random string of numbers (a token). Your database only stores the token. If your site gets hacked, the hacker finds useless tokens instead of raw Visa numbers. That protects you from catastrophic liability.
Your merchant provider, meanwhile, requires you to maintain baseline PCI compliance annually. Ignore it, and you’ll get hit with non-compliance fees every single month until you fill out the security questionnaires.
Frequently Asked Questions
Do I need both a payment gateway and a merchant account?
Yes. To accept credit cards online, you must have a way to process the transaction (gateway) and a bank account designed to hold and clear the funds (merchant account). Many modern providers bundle these two together, but functionally, both components are always present.
Why did my payment processor suddenly freeze my account?
If you use an aggregated provider (like Stripe or PayPal), sudden spikes in sales, high refund rates, or selling in a “high-risk” category can trigger automated fraud algorithms. They freeze accounts first and ask questions later to protect themselves from chargeback liability.
When should I transition from an aggregated account to a dedicated merchant account?
As a general rule of thumb, once your monthly credit card processing volume consistently exceeds $10,000 to $20,000, you should look into a dedicated merchant account with interchange-plus pricing to significantly lower your processing fees.
Are payment gateways responsible for chargebacks?
No. The gateway simply passes the transaction data. Chargebacks are managed by your merchant account provider and the card networks. However, some gateways offer built-in fraud prevention tools that help mitigate your chargeback exposure.