Wire Transfer Vs Ach Transfer: Which Is Cheaper for International Payments?
I’ve lost count of how many times a frantic founder has slid into my inbox with the same exact panic attack: “I just sent five figures overseas, the bank ate three hundred dollars in hidden fees, and my vendor hasn’t seen a dime.” Here’s the ugly truth about moving money across borders—traditional banking infrastructure treats your capital like a piñata. If you aren’t paying attention to the mechanics behind a wire transfer versus an ACH transfer, you are essentially volunteering to set cash on fire. Let’s look at how the plumbing actually works, where the hidden costs live, and how you stop bleeding margin every single time you pay a global supplier or remote contractor.
- • The Anatomy of Moving Money Across Borders
- • Wire Transfer Vs ACH Transfer: Breaking Down the Real Expenses
- • Hidden Traps: Why "Free" Transfers Often Cost the Most
- • How to Choose the Right Method for Your Business Size
- ↳ Can I send a standard US ACH transfer directly to an international bank account?
- ↳ Why did my international wire transfer arrive short of the amount I sent?
- ↳ What is the absolute cheapest way to pay overseas contractors?
- ↳ Do exchange rate markups matter more than transfer fees?
Key Takeaways & Quick Overview
AI Verified
- ✔Wire transfer vs ach transfer: which is cheaper for international payments? i’ve lost count of how many times a frantic founder has slid into my inbox with the same exact panic attack: “i just sent five figures overseas, the bank ate three hundred dollars in hidden fees, and my vendor hasn’t seen a dime.
- ✔” here’s the ugly truth about moving money across borders—traditional banking infrastructure treats your capital like a piñata.
- ✔If you aren’t paying attention to the mechanics behind a wire transfer versus an ach transfer, you are essentially volunteering to set cash on fire.
- ✔Let’s look at how the plumbing actually works, where the hidden costs live, and how you stop bleeding margin every single time you pay a global supplier or remote contractor.
The Anatomy of Moving Money Across Borders
Most people think moving money from Point A to Point B is like sending an email. Type the routing number, hit send, walk away. I wish. The reality involves a tangled web of correspondent banks, middle-men clearinghouses, and legacy protocols designed decades before the internet was even a consumer product.
When you look at domestic payments, ACH (Automated Clearing House) is the cheap, reliable workhorse of the US financial system. It processes batches of transactions a few times a day. It costs pennies. Sometimes, it’s completely free. But the moment you try to use standard domestic ACH for an international payment, you hit a brick wall. Most domestic ACH rails simply do not speak foreign currencies natively. According to Federal Reserve international ACH rules, trying to force a standard domestic ACH routing sequence across international borders usually results in a rejected transaction, a frantic call to customer support, or a painful reverse-fee penalty.
On the flip side, we have wire transfers. These are direct, bank-to-bank communications typically moving over the SWIFT network data infrastructure. They are fast. They are secure. They also come with price tags that will make your eyes water. Let’s break down the actual costs.
Wire Transfer Vs ACH Transfer: Breaking Down the Real Expenses
Let’s get one thing straight right out of the gate: if you are trying to send a direct ACH transfer internationally to a foreign bank account in a foreign currency, you are likely using the wrong tool for the job. Standard ACH is built for domestic movement. However, certain modern fintech platforms offer “International ACH” or local clearing alternatives that mimic ACH speeds and low costs. But traditional bank wires? They are a completely different beast.
Here is what you actually pay for when you initiate a traditional outgoing international wire:
- The Originating Bank Fee: Usually ranges from $30 to $50 flat.
- The Intermediary Bank Cut: If your bank doesn’t have a direct relationship with the recipient’s bank, the money hops through one or two correspondent banks. Each one takes a slice, often $10 to $25 per hop.
- The Receiving Bank Fee: The foreign bank often charges the recipient just for accepting the wire. That means your vendor gets short-paid, and guess who has to fix that awkward conversation? You do.
- The FX Markup: This is the silent killer. Banks rarely give you the real mid-market exchange rate. They bake a 1% to 4% markup right into the currency conversion. On a $50,000 transfer, a 3% markup is $1,500 gone into thin air.
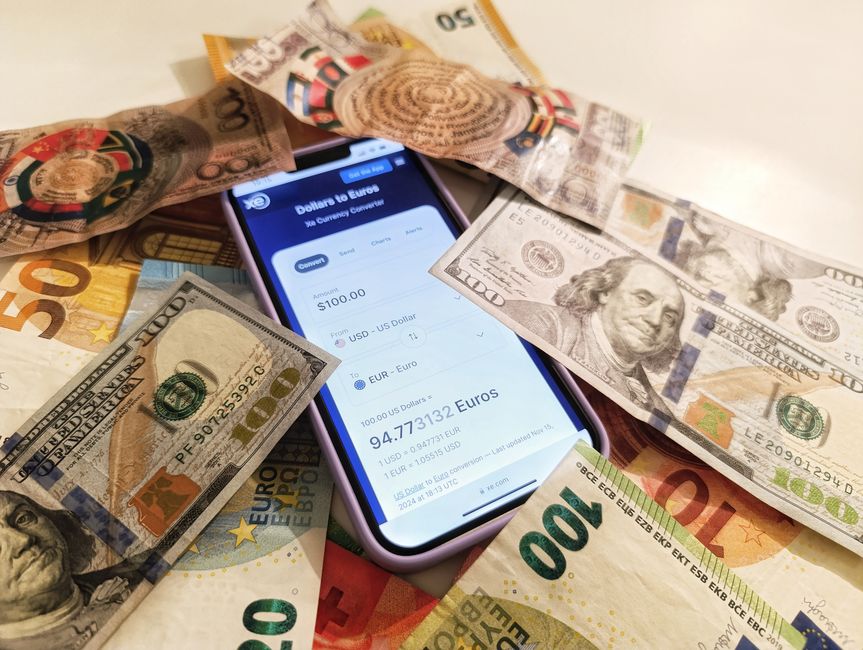
So, is an ACH-style local clearing network cheaper? Absolutely. If a provider lets you initiate a local ACH equivalent transfer in the destination country’s local currency, you bypass the SWIFT intermediary chain entirely. You pay a tiny flat fee or a transparent percentage, and the exchange rate is infinitely closer to what you see on Google.
Hidden Traps: Why “Free” Transfers Often Cost the Most
Trust me on this: nobody in international finance gives away free lunches. When a traditional bank advertises “zero-fee international wire transfers,” check the fine print immediately. You will almost always find the catch buried in the exchange rate spread.
Let’s run a quick mental simulation. Bank A charges a $45 flat wire fee, but gives you a fair mid-market exchange rate minus 0.5%. Bank B charges $0 for the wire transfer, but jacks up the exchange rate markup by 3.5%. For a $10,000 transfer, Bank A costs you $45 plus about $50 in FX spread ($95 total). Bank B costs you $0 in fees, but $350 in hidden currency markup. Which one is actually cheaper? Exactly. Stop looking only at the flat fee line item on your bank statement.
How to Choose the Right Method for Your Business Size
Different transaction sizes demand entirely different strategies. If you are moving micro-amounts—say, under $500—traditional wires are financial suicide. A $40 wire fee on a $200 invoice is a 20% tax on your transaction. For smaller, recurring international payouts, you want local ACH-style batch transfers through specialized cross-border payment rails like Wise Business, OFX, or Payoneer.
For massive, enterprise-level capital movements—like buying real estate abroad or executing a six-figure manufacturing deposit—traditional wires, while expensive, offer a legal paper trail and a level of bank-guaranteed certainty that some modern digital wallets struggle to match for large single-tranche movements. Even then, smart CFOs use specialized currency brokers to lock in forward contracts rather than letting their retail commercial bank dictate the spot rate.
Frequently Asked Questions
Can I send a standard US ACH transfer directly to an international bank account?
Generally, no. Standard US ACH routing numbers and account structures are not recognized by foreign banking systems for direct cross-border deposits. Attempting to do so usually results in a failed transaction.
Why did my international wire transfer arrive short of the amount I sent?
This is caused by intermediary or correspondent banks taking deductions along the SWIFT network path, combined with flat fees charged by the receiving bank upon deposit.
What is the absolute cheapest way to pay overseas contractors?
Using specialized multi-currency business accounts that utilize local clearing networks (essentially local ACH equivalents in the contractor’s home country) is almost always significantly cheaper than traditional SWIFT wire transfers.
Do exchange rate markups matter more than transfer fees?
Almost always, yes. While a $45 flat wire fee hurts your feelings, a bloated 3% to 4% foreign exchange markup on a large transfer will drain thousands of dollars from your bottom line without you ever seeing a distinct fee item on your receipt.